A chattel is a personal, movable item in a property:, furniture, freestanding appliances, curtains, anything you could take with you without leaving a mark on the walls, floors, or fittings around it.
The term comes up a lot in buying and selling, because it determines what’s included in a sale, and sometimes how much stamp duty land tax you’ll pay. Knowing the difference between a chattel and a fixture can save a lot of back-and-forth once contracts are exchanged.
Related: What is a restrictive covenant? A buyer’s guide to understanding property restrictions
What is the difference between chattels and fixtures
Fixtures are attached to a property permanently, and the law treats them as part of the building itself. Chattels aren’t, they were never intended to remain in place.
The test used to draw the line between the two is called the degree and purpose of annexation. It looks at how something is fixed in place and why it’s there. Screwed, bolted, or plumbed in with the intention of staying, and it’s likely a fixture. Plugged in, freestanding, or removable without damage, and it’s likely a chattel.
The purpose matters as much as the method of attachment. A heavy bookcase simply resting against a wall for stability is still a chattel, since it isn’t fixed with the intention of becoming part of the building. A mirror screwed directly into the plaster, on the other hand, is more likely to be treated as a fixture, even though removing it wouldn’t cause much damage, because the intention behind fixing it was permanence.
Examples of chattels and fixtures
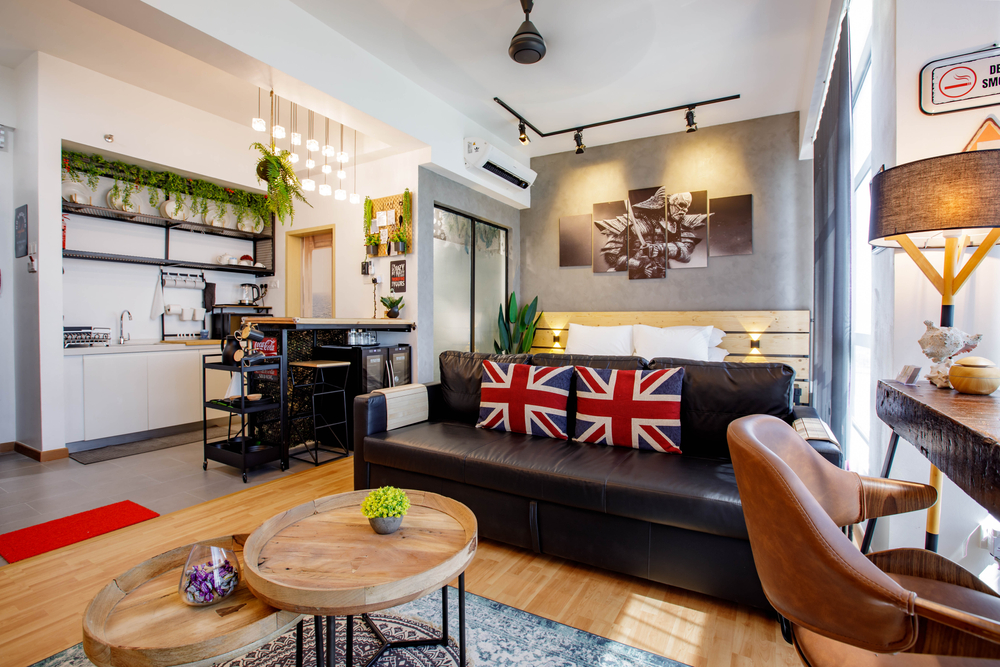
A fitted kitchen, a built-in wardrobe, a radiator, a wired-in light fitting, integrated appliances, and a garden wall would typically all count as fixtures. A freestanding sofa, a rug, a set of curtains, a freestanding washing machine, garden furniture, and ornaments would typically count as chattels.
There are grey areas too. A freestanding cooker that’s been in the same spot for a decade, a fitted carpet laid without adhesive, or a shed that’s simply resting on paving slabs rather than fixed down, can all go either way depending on the specifics. This is exactly why it’s worth putting things in writing rather than assuming either side has the same expectation.
Related: A buyer’s guide to repossessed properties
Why it matters when you buy or sell
Fixtures come with the property automatically unless the seller says otherwise. Chattels don’t, they’re only included if both sides agree they are. A buyer might expect the integrated appliances to stay. A seller might expect the dining table to go with them. Without something written down, those two expectations don’t always align.
This is what the fixtures and fittings form is for. Known formally as the TA10, it’s completed by the seller during conveyancing and sets out what’s included, excluded and what might be available for separate negotiation. Once contracts exchange, it becomes legally binding, which makes it far more reliable than anything discussed informally during a viewing.
The stamp duty land tax angle
Fixtures count towards the property price for stamp duty purposes. Chattels generally don’t, provided the value attributed to them is genuine rather than inflated to reduce the taxable price.
HMRC pays close attention to this, particularly near a tax threshold. Any figure attached to chattels needs to reflect what those items are actually worth, factoring in age and condition, and it needs to be documented properly rather than agreed informally. Overstate the value to reduce a tax bill, and it can trigger a challenge, sometimes resulting in more tax being owed once HMRC has reviewed it.
Related: Guide to selling an inherited property in the UK
Chattels and chattel mortgages
It’s worth mentioning a related but separate term you might come across: a chattel mortgage. This isn’t about buying or selling a home. It’s a type of finance agreement, more commonly used for vehicles or business equipment, where the item itself is used as security for a loan while the borrower keeps possession and use of it. The lender holds an interest over the chattel until the loan is repaid in full. It shares the same underlying idea of movable property, but it belongs to a different area of finance rather than residential property transactions.
Related: The Base Rate Cut and What It Could Mean for Property in 2026
What’s worth doing
It helps to walk through the property beforehand and be specific about what you expect to stay and what you expect to go, then get it down in writing rather than relying on memory later. This is worth doing for smaller items in addition to larger fixtures like a fitted kitchen, since light shades and garden furniture can just as easily lead to a misunderstanding.
If you’re unsure whether something in a property counts as a fixture or a chattel, your local Whitegates branch can help clarify.