Taking your first step onto the property ladder is one of the biggest financial decisions you will make. Pontefract offers a range of homes for buyers to compare, but affordability depends on your deposit, income and the property you choose. For an October 2026 move, use the worked purchase example below to plan your costs. During autumn viewings, check heating, maintenance and daylight as well as price, so your budget covers both the purchase and winter running costs.
This guide from Whitegates Pontefract breaks down every cost you need to know about in October 2026, from your deposit and legal fees to your monthly mortgage payment. Whether you are saving hard, ready to view, or simply curious about what it all adds up to, read on.
What does a first home in Pontefract actually cost?
This guide uses a £185,000 purchase as an illustration, rather than a verified October 2026 first-time buyer average for Pontefract. It provides a consistent way to calculate deposit, tax and mortgage costs; compare current homes and completed sales before choosing your own budget.
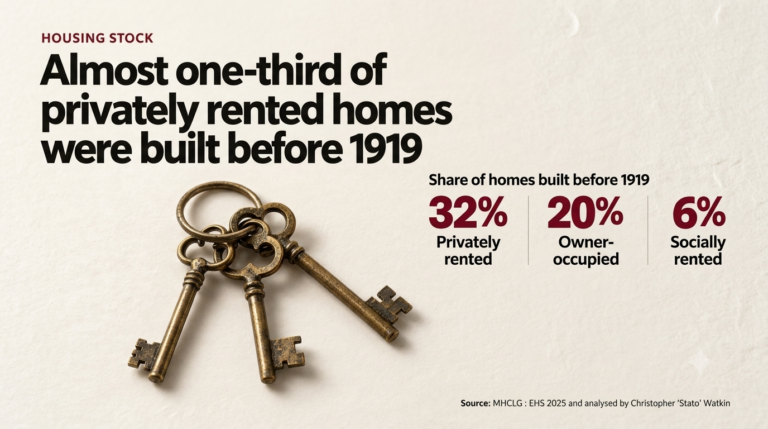
Pontefract sits firmly within the WF8 postcode, and across the town there is genuine variety – from Victorian terraces to modern new-build homes – giving first-time buyers real choice at different price points.
Stamp Duty Land Tax: the saving that changes everything
Under the April 2025 SDLT thresholds, an eligible first-time buyer pays no SDLT up to £300,000 and 5% on the portion above that up to £500,000. Relief is unavailable if the total price exceeds £500,000. All purchasers must meet the first-time buyer conditions; additional circumstances, including non-resident surcharges, can affect liability.
At the illustrated £185,000 price, an eligible purchase without a surcharge has £0 SDLT. An ordinary main-residence purchase without first-time buyer relief has £1,200 SDLT: 2% of the £60,000 above £125,000.
Breaking down your upfront costs
Understanding the full picture of what you need in cash before you collect the keys is essential. Here is a realistic breakdown based on the Pontefract market in October 2026.
Your deposit
A 10% deposit on the illustrated £185,000 purchase is £18,500. Some products allow a 5% deposit, subject to eligibility and affordability checks. Compare actual rates and fees; a 10% deposit is an example, not a requirement or a universal guarantee of the best deal.
Legal fees and conveyancing
Conveyancing costs in England typically range from £1,000 to £2,500 depending on the complexity of the transaction, the solicitor you choose, and whether the property is freehold or leasehold. Budget towards the higher end if you are purchasing a new-build or a property with any title complications.
Survey costs
A mortgage valuation is usually arranged by your lender, but it is strongly advisable to commission an independent survey. A HomeBuyer Report costs approximately £400–£600, while a full structural survey can reach £700–£900 or more. For older terraced properties – common in areas like Chequerfield and Friarwood – a survey is particularly worthwhile.
Moving and other costs
Removal costs, utility connection fees, initial furnishing, and any immediate maintenance work can add £500–£1,500 to your total outlay. It is easy to underestimate this, so build a buffer into your budget.
Total cash required
With an £18,500 deposit, the quoted legal, survey and moving ranges give approximately £20,400–£23,400 before mortgage product fees and any additional work. A £21,800 total is one illustration within that range, not a fixed cash requirement. Obtain quotations and add a contingency.
What will your monthly mortgage cost?
For illustration, a £166,500 repayment mortgage at 5.5% over 25 years costs approximately £1,022.46 per month, excluding fees added to the loan. This is a calculation assumption rather than a verified current mortgage offer; use a lender’s illustration for the actual product and term.
Compared with a hypothetical £825 monthly rent, that mortgage payment is about £197 more, not £148. The rent is not established here as a current WF8 average, and ownership also involves repairs, insurance and any service charges. Compare the total costs of the homes actually available to you.
Using a Lifetime ISA to build your Pontefract deposit
If you are still saving, the Lifetime ISA (LISA) is one of the most powerful tools available to first-time buyers in the UK. You can save up to £4,000 per year and receive a 25% government bonus – up to £1,000 annually – on top of your contributions.
A qualifying first-home purchase must cost no more than £450,000, use an eligible mortgage and a conveyancer, and take place at least 12 months after the first payment into the LISA. You must intend to live in the home. Opening and contribution age limits also apply; other withdrawals can incur a 25% charge.
The best neighbourhoods for first-time buyers in Pontefract
Pontefract offers several distinct areas that are particularly well-suited to first-time buyers, depending on your budget and priorities.
Chequerfield and Friarwood
These established residential areas offer terraced homes from around £130,000, making them among the most affordable entry points in the town. Both neighbourhoods have good local amenities and a strong sense of community, and they are popular with buyers looking to maximise their purchasing power.
Featherstone (WF7)
Just to the west of Pontefract, Featherstone offers terraced properties from approximately £120,000 – the lowest entry point in the wider area. It is a practical choice for buyers who need to stretch their deposit further while remaining within easy reach of Pontefract town centre and its amenities.
Monkhill and Tanshelf
For first-time buyers with commuting in mind, Monkhill and Tanshelf offer a more central location with strong transport links. Pontefract Monkhill railway station provides direct services to Leeds, making these neighbourhoods particularly appealing to buyers who work in the city but want the affordability of Pontefract living.
Prince of Wales Colliery: a new-build option
The former Prince of Wales Colliery offers phased new-build options, but a brownfield allocation for potential homes is different from planning permission, construction or homes available now. Check the particular parcel, developer and release dates. Compare actual new-build prices, warranties and energy specifications with equivalent resale homes rather than applying an unverified 25.1% premium.
Is now a good time to buy in Pontefract?
October 2026 is a useful time to compare homes and establish your buying position, but it is not automatically the best market window. Your deposit, borrowing capacity, running costs and the suitability of the property should guide the decision.
Eligible SDLT relief and a qualifying LISA can reduce some upfront costs. They do not apply to every buyer, and Pontefract’s affordability should be assessed against your income and the actual properties available rather than an unsupported regional ranking.
Ready to take your first step?
At Whitegates Pontefract, we work with first-time buyers every day – helping them understand their options, find the right property, and move forward with confidence. Whether you are at the early planning stage or ready to start viewing, our team is here to guide you through every step of the process.
Book a valuation today if you are considering selling a property to fund your next move, or get in touch with the Whitegates Pontefract branch directly to discuss your first-time buyer search. We would love to help you make Pontefract your home.